-
Breaking Through the Pressure: A Practical Approach to UK Debt Relief
There is an entirely unique brand of exhaustion that comes from living with financial pressure. It usually starts quietly—a late fee here, a shifted balance there—until one day you realize you are spending half your mental energy calculating how to stretch your remaining cash to cover the next electricity bill or grocery run. If you are sitting there tonight running those stressful loops through your head, staring at an unopened stack of letters, please know you are not the first person to feel entirely cornered by it, and you certainly won’t be the last.
Most people try to outrun the pressure in total isolation. You juggle credit cards, borrow a small amount from a relative just to keep things afloat, or skip meals so you can meet an upcoming payment deadline. It feels like walking across a tightrope in high winds, waiting for the ground to give way. But white-knuckling your way through hidden debt is a losing battle, and more importantly, it isn’t a life you have to keep living.
The UK financial landscape actually has robust, legally recognized safety nets built right into it. Lenders aren’t going to send letters advertising these options because they profit heavily from keeping you locked into minimum payments and compounding interest. Yet, those legal frameworks exist to give everyday people a clean slate or a structured breathing space when life throws an unexpected curveball.
To find any real relief, you have to push the panic aside for a moment and look purely at your household numbers. Sit down with a blank piece of paper and write down what actually lands in your bank account every month, followed by your absolute non-negotiables—your rent or mortgage, council tax, energy bills, food, and basic transport to work. Whatever is left over after those essentials are handled is your true disposable income. Under UK rules, creditors cannot legally demand that you starve or lose your home just to service an old loan.
That disposable income figure is what determines your next move:
-
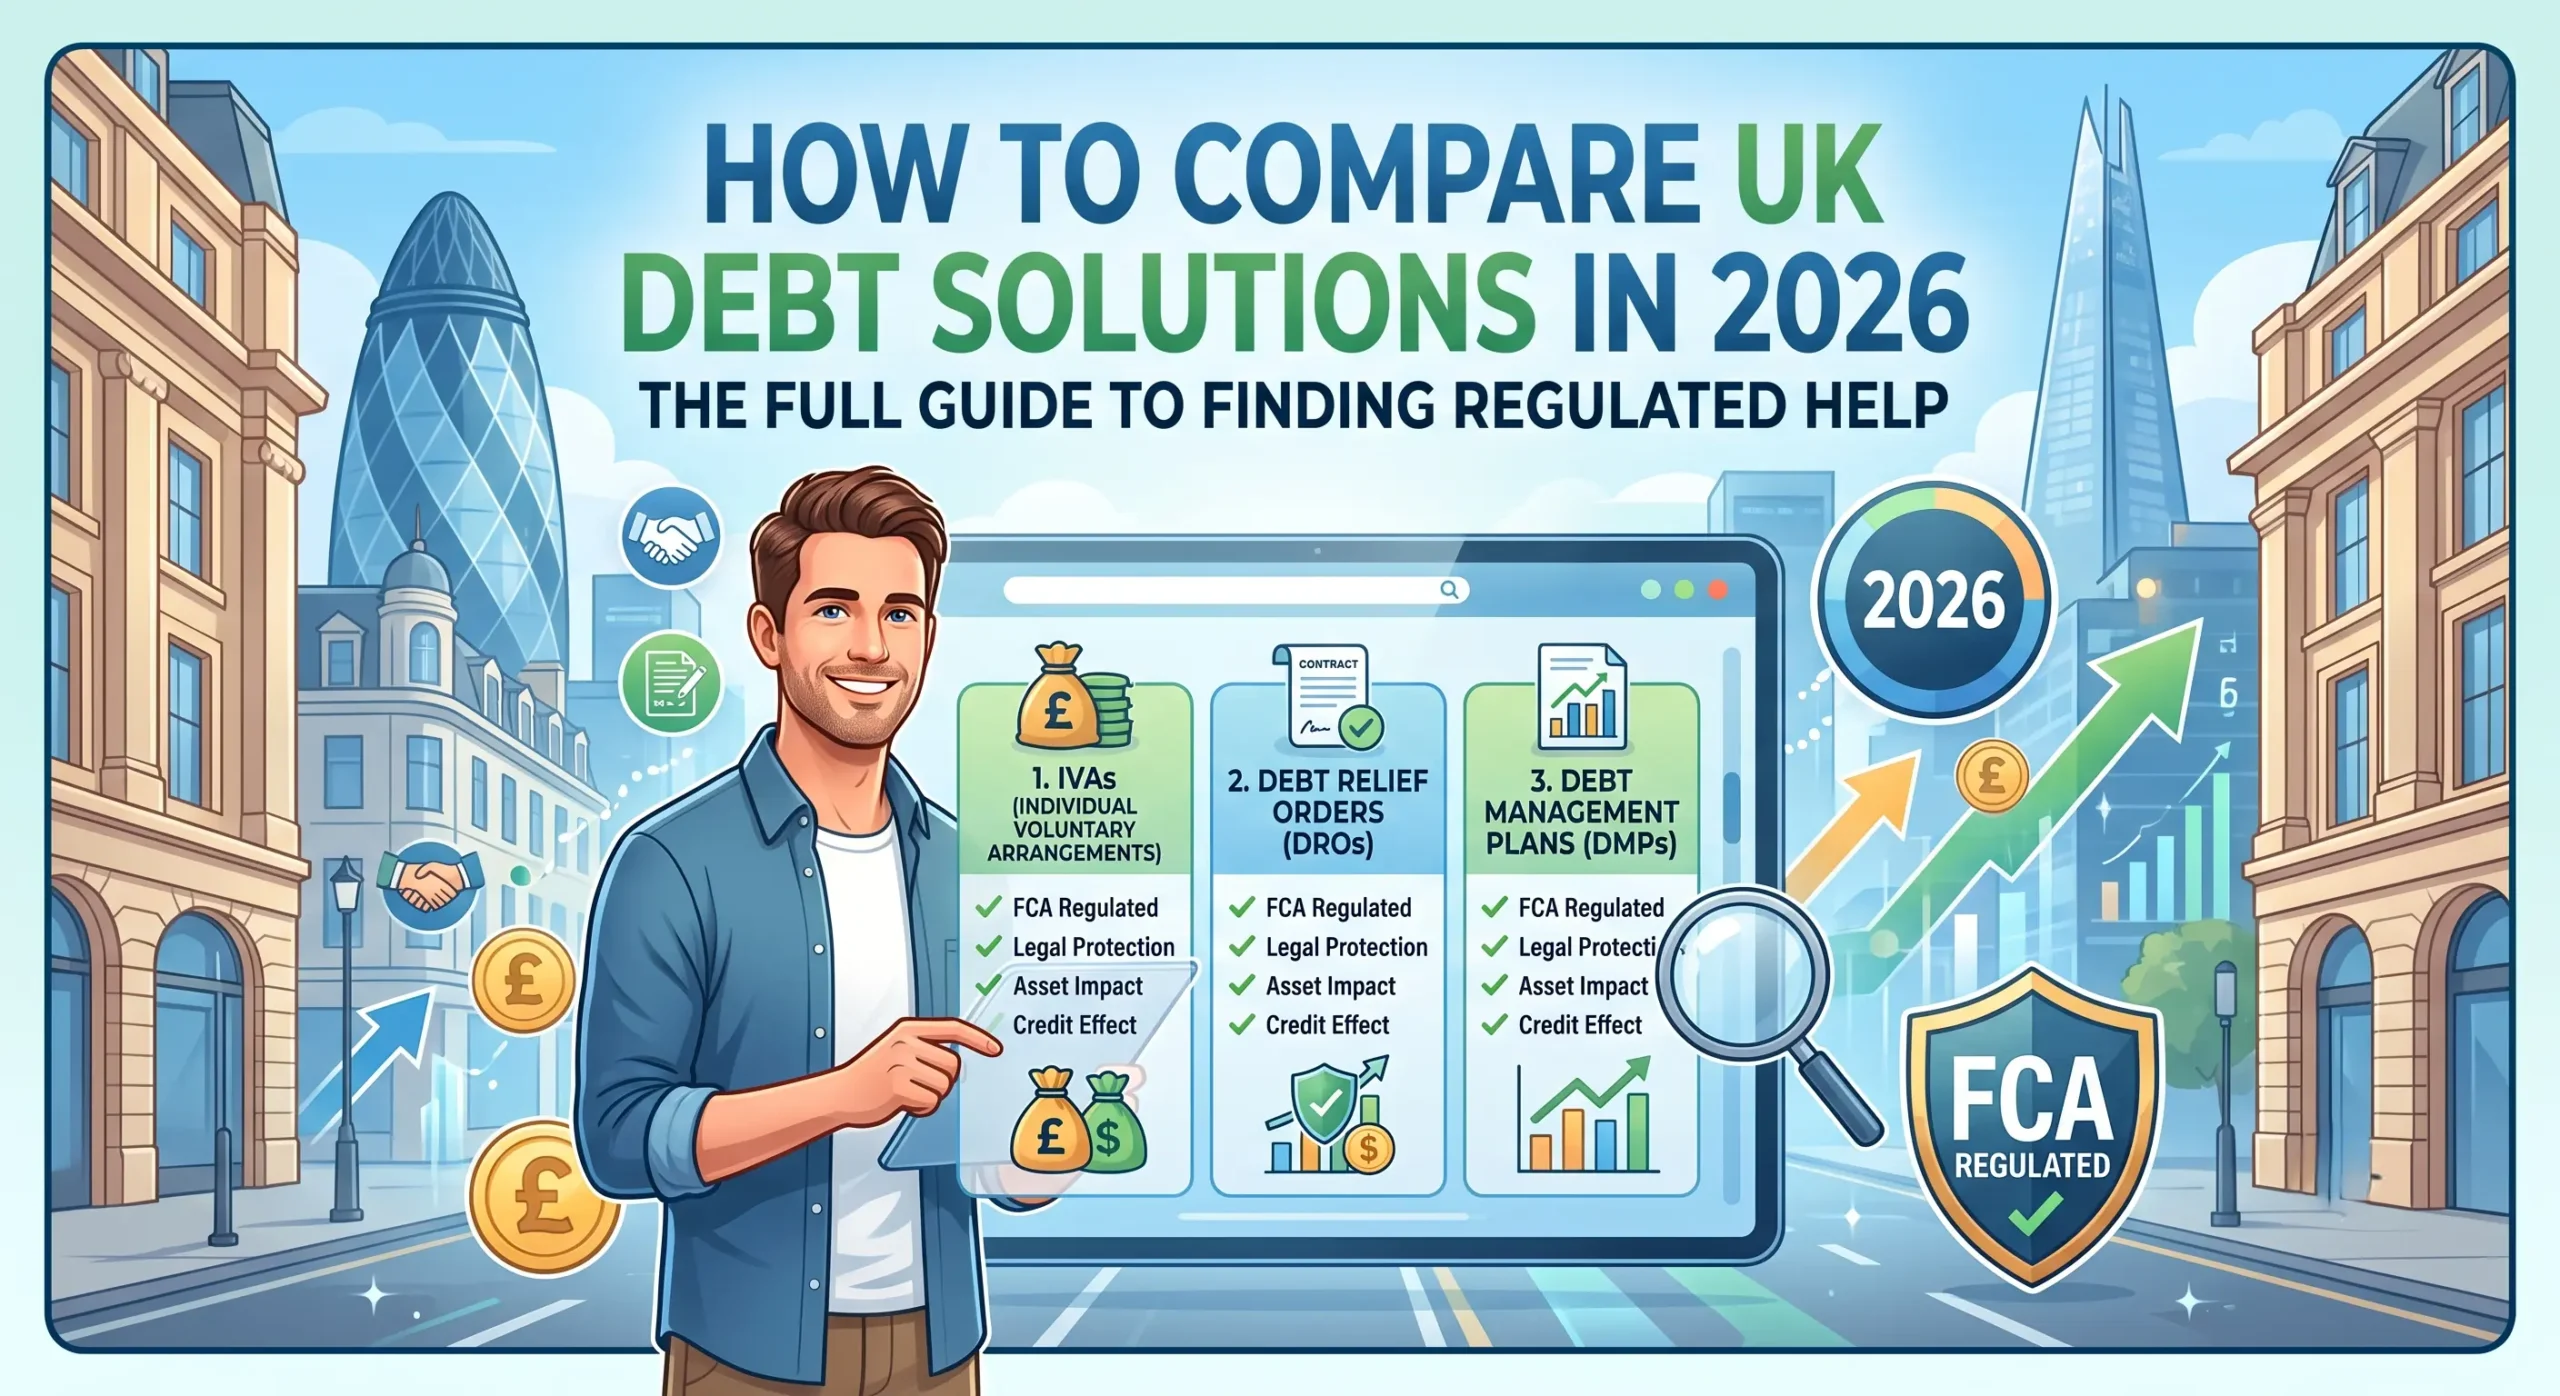
If you own a home and have a steady job: An Individual Voluntary Arrangement (IVA) might let you make one manageable monthly sum for a fixed period while protecting your property and clearing the rest at the end.
-
If you rent and have very little money left each month: A Debt Relief Order (DRO) acts as a low-cost reset button. Qualifying debts under £50,000 are frozen for 12 months, and if your circumstances haven’t improved, those debts are cleared completely.
-
If you want to repay what you owe without formal insolvency: A Debt Management Plan (DMP) allows you to negotiate a single reduced payment with your creditors so you can pay back what you owe at a pace that fits your real budget.
Because these options carry real long-term implications for your credit file, rushing in without clear information can lead to wrong choices. Taking a few minutes to read through a detailed resource on How to Compare UK Debt Solutions gives you the knowledge you need to evaluate your options with complete confidence.
The non-stop worry, the unopened mail, and the fear of answering your phone do not have to be your everyday normal. You don’t have to figure this out on your own or deal with pushy sales tactics. At Debt Help Support, we keep things entirely simple and human by listening to your story and directly connecting you to the respective authorized parties, licensed Insolvency Practitioners, and FCA-regulated specialists who can set up legal protections for you. The moment you take that first step, the harassment stops, interest can be frozen, and you finally get a clear, realistic path toward becoming debt-free.
debthelpsupport.co.uk
How to Compare UK Debt Solutions in 2026: The Full Guide to Finding Regulated Help
Being in over your head with your personal debt can be isolating but you don’t have to go through it alone. You need clear, objective...
-
Sorry, there were no replies found.
Log in to reply.